Livin' La Vida Luna y Luca
The weather gods are blessing us deep into October after raining every weekend in September, and we ain't mad about it. 🎃
"Be Greedy When Others Are Fearful...
... and fearful when others are greedy"
Warren Buffett said that & it's great advice.
But Buffett forgot to mention one thing: how hard it is to practice what he preaches.
Right now, I'm fearful. So are most of my colleagues in single-family home development.
By Buffett's logic, that means it's time to go big.
Deploy more capital. More resources. Double down. Gobble up properties to tear down and deliver new homes to the market.
But that's hard to do when the writing on the wall says things will get worse before they get better.
See Polymarket chart below:
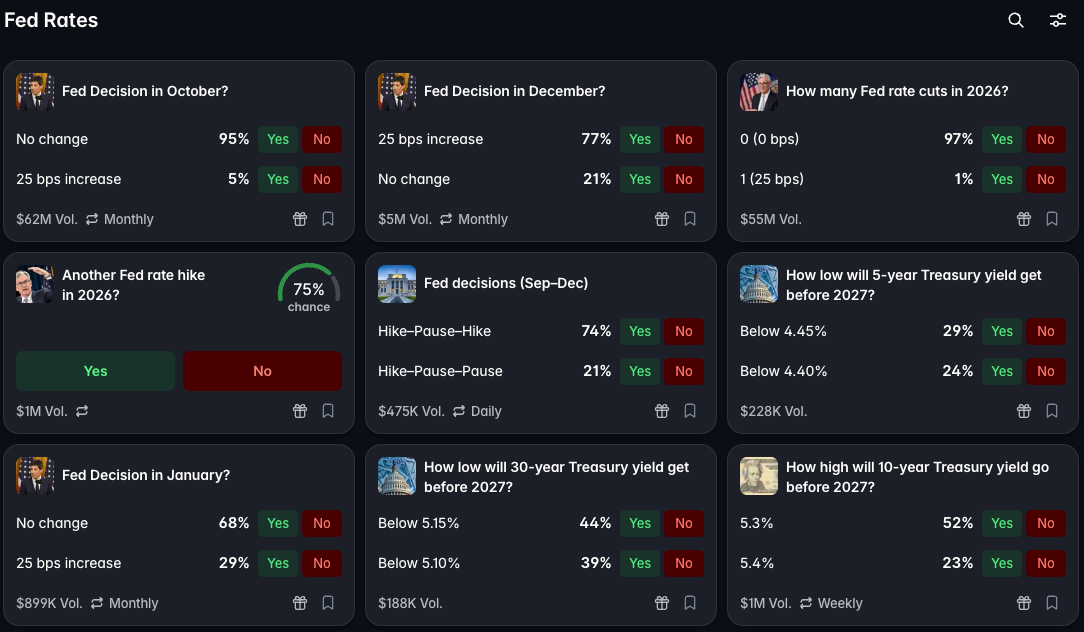
The market is betting on the Fed Rate to increase by <25bps in the next 90 days.
They're not directly correlated, but we can safely assume the 30-year fixed rate likely goes up in lock step.
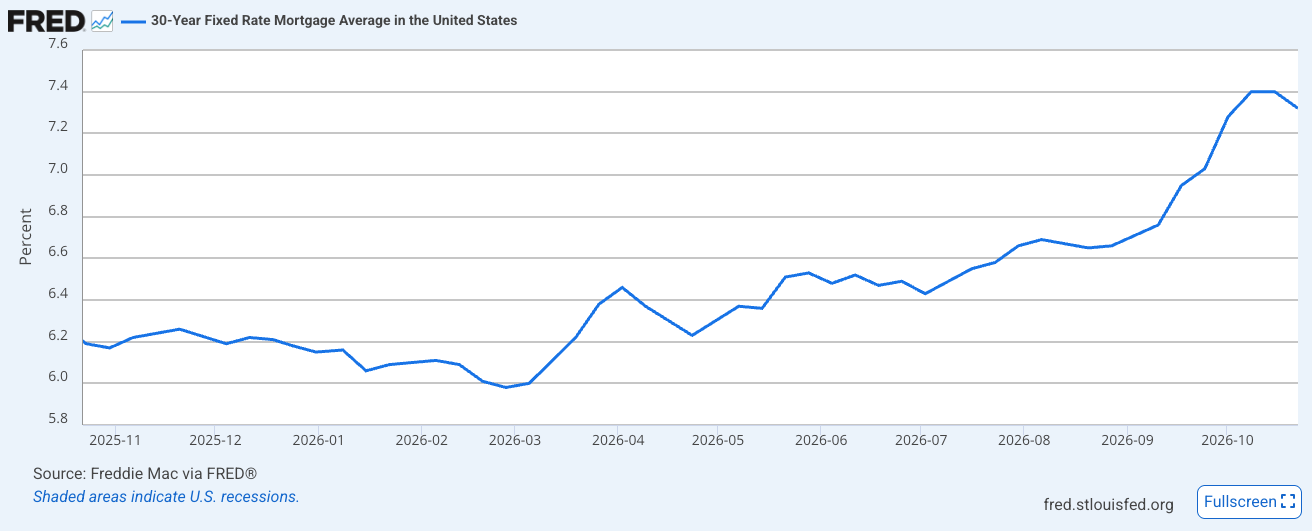
We're currently sitting at 7.4% for the 30-year fixed rate.
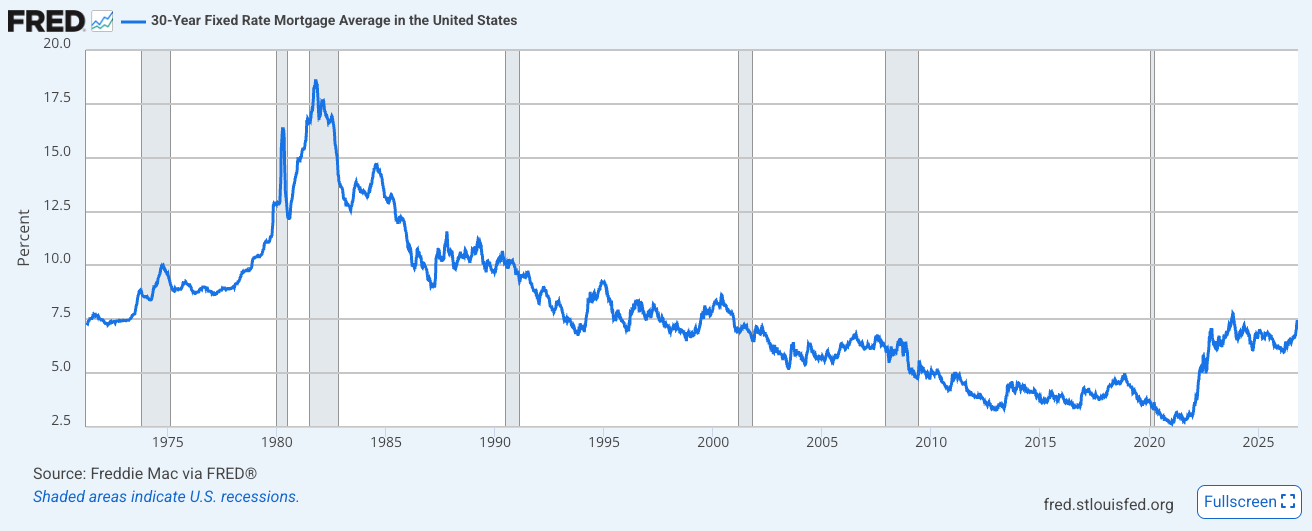
Which is pretty much the highest it's been since Y2K.
And as anyone who took Econ 101 knows, if rates go up, prices go down.
So if I believe rates are going up, I also have to believe prices will stay flat or go down.
Flat isn't really a problem. We underwrite to printed comps & project zero growth despite delivering homes 12 months later.
This only becomes a problem if rates rise so much that home prices fall.
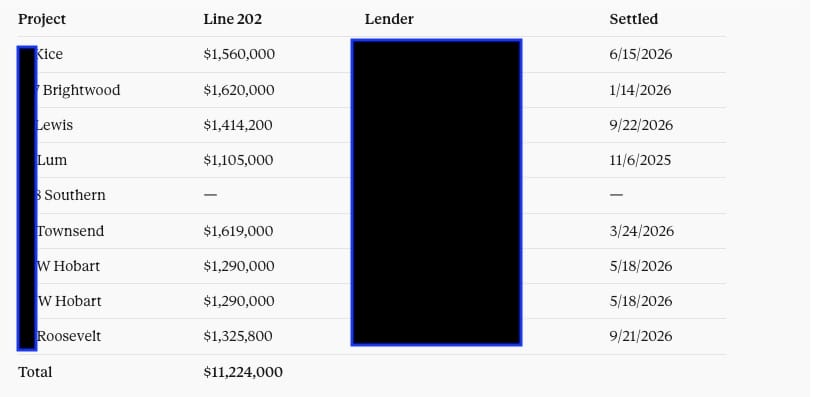
To stress test my portfolio, I added up what I owe hard money lenders. Line 202 shows purchase money loan + construction loan: $11.224M total.
We average 12 months from purchase closing to sale closing. But each loan matures at 18 months. So the stress test assumes we hold every home 6 months longer than usual.
Six extra months of interest at 10% on $11.224M is ~$560K. That's a big number, but it's not debilitating, assuming we still hit our underwritten exit price.
Insulated Markets
We only build homes in a handful of towns in Northeast NJ. They all have:
- Access to great schools (Public & Private)
- Midtown Direct Train to NYC
- Fair property taxes
We're not building starter homes for rate-sensitive buyers fixated on their monthly nut. Everyone would be better off leaving that game to the nationals like Lennar, Pulte, Ryan, DR, & K.Hov.
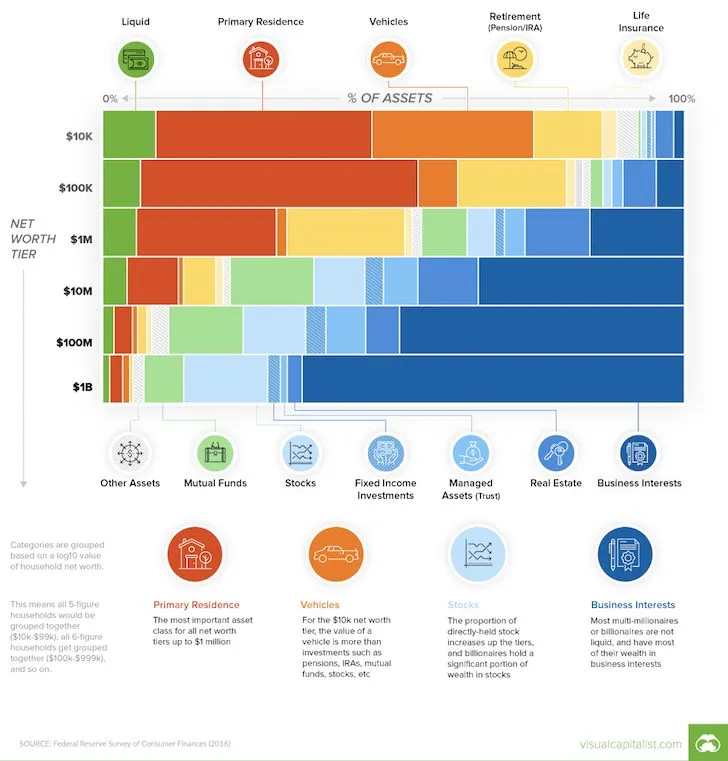
We build homes for balance sheet buyers. These are people whose home equity is a relatively low percentage of net worth.
For example...
- The last $2.85M home we sold was to a couple that earns 7-figures+ in annual salary, excluding RSUs & bonuses.
- The $2.5M home we sold before that was paid for with a combination of $1.5M down payment and $1M loan. When's the last time you heard of someone putting more money down than they borrowed?
- Finally... the $2.25M home we sold at the end of 2025 was to a family that had >$2.25M in a savings account with Goldman Sachs. 🤯
Seeing this level of wealth never ceases to amaze me, but it's out there, and it seems abundant. As long as we keep putting out a product they like in markets they want to be in, I think we'll be ok.
Revisiting Reconvene
The last Breakout Session I attended at Reconvene 2026 was "The State of the Debt Market".
It was off the record, so I won't mention any names or details, but the sentiment was essentially this:
- Lenders are desperate to deploy capital
- Yield spreads have never been tighter
- Anemic # of deals getting done since 10-yr shot up
- Equity Investors of risk assets are on the sidelines because they can yield 5%+ from T-Bills & Indexes are ripping.
All of that to say, to the victor go the spoils.
Banks are lending (@ relatively attractive rates) to people willing to take on the risk. If you're lucky enough to be in a position to raise equity for deals, you might just look like the Oracle of Omaha as we climb our way out of the current cycle.
...or you'll end up like Rick Guerin (Buffett & Munger's 3rd partner who got margin-called and sold his Berkshire shares for about $40 each back in '74).
Who tf knows 🤷🏽♂️
✌🏽❤️